
Homeowners community insurance on the Costa del Sol: what it covers and who decides
President or owner? Discover what community insurance covers in Marbella, what it doesn't, and why it's essential. Request a free, no-obligation quote.
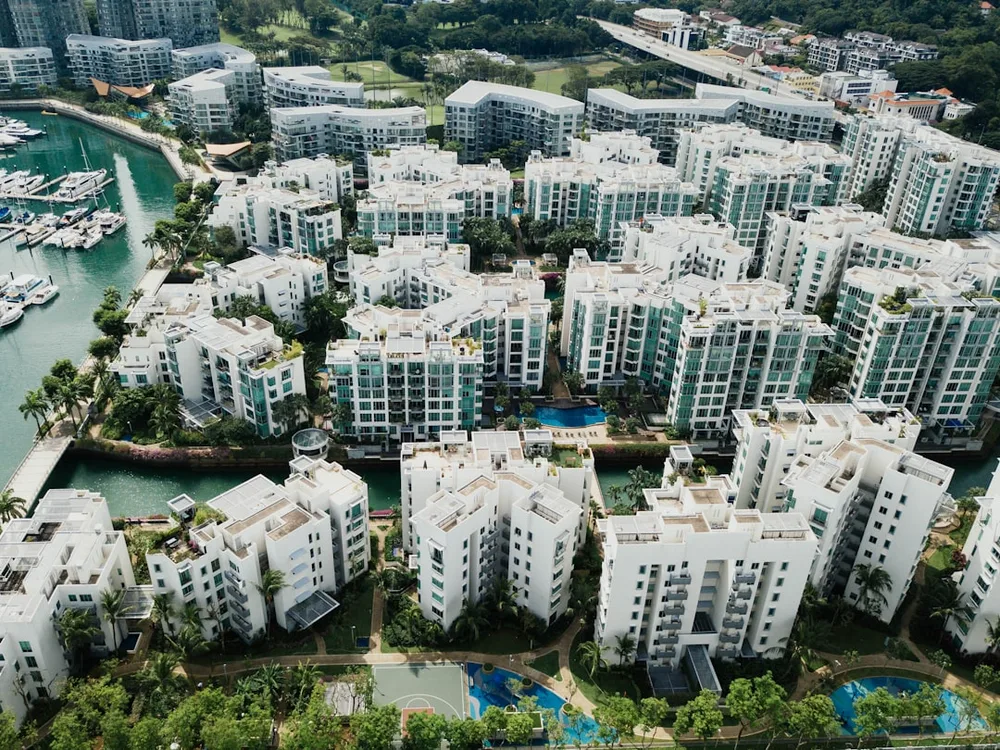
If you are the president of a residents' community or a property owner in a urbanisation on the Costa del Sol, you know better than anyone what managing shared spaces involves: swimming pools, gardens, garages, lifts… And when something goes wrong — a burst pipe, a visitor who slips on the stairs, a fire in the storage room — the question is always the same: who pays for this? That is where homeowners community insurance in Marbella comes in.
What exactly does community insurance cover?
The community insurance policy protects everything that belongs to the community as a whole, not to individual owners. In essence, it covers four main areas:
- Damage to the building and shared areas: fires, explosions, weather events, breakage of glass in communal areas, vandalism…
- Water damage: leaks, burst pipes, and seepage affecting communal elements or the flats below. This is one of the most frequent claims in urbanisations in the area.
- Community public liability: covers third-party claims for injuries or damage occurring in communal areas. If a resident or visitor is injured at the pool, in the car park, or on the stairs, the community is liable — and so is the insurer.
- Legal defence: covers legal costs if the community becomes involved in litigation, which is more common than you might expect in areas with many urbanisations and international property owners.
What does community insurance NOT cover?
This is the point that causes the most confusion, and it is worth making it clear: community insurance does not cover the interior of individual properties. Furniture, appliances, internal renovations, or damage inside each owner's flat are their own responsibility.
That is what individual home insurance is for — something every owner should take out separately. The two policies complement each other; they do not overlap.
Who takes out and who decides on homeowners community insurance in Marbella?
The decision to take out a policy — and to choose which insurer — rests with the owners' meeting (junta de propietarios), usually on the recommendation of the property manager. It is the owners' meeting that approves the policy and sets the insured sum for the building.
The cost is shared among all owners in proportion to their participation coefficient, just like other community expenses. So, even if you are not the one taking out the policy directly, as an owner you have every right to request that the policy be reviewed, that quotes be compared, or that the cover be improved.
In Marbella urbanisations with swimming pools, large gardens, barbecue areas, or communal gyms, the exposure to risk is considerably greater than in a standard urban block of flats. That needs to be reflected in the level of cover.
Frequently asked questions about community insurance
Is community insurance compulsory?
In Spain, there is no national law that generally requires communities to hold insurance, although some regional governments do impose minimum cover requirements. That said, the vast majority of communities do have it — and banks providing mortgage finance typically require it. Operating without it means taking on an enormous financial risk.
Does it overlap with my home insurance?
No, they complement each other. Community insurance protects the shared elements of the building; home insurance protects the interior of your property. You can read more about how the two work together in our article on the other side of your communal swimming pool: legal responsibilities and insurance.
Who pays if someone has an accident in a communal area?
The homeowners community, as the party responsible for maintaining communal areas, may face civil or even criminal claims. The public liability cover within the community insurance policy is what meets those claims: compensation payments, medical expenses, legal fees… This is one of the key reasons why this cover is indispensable in urbanisations with pools and gardens.
How is the insured sum for the building calculated?
The sum insured must reflect the reinstatement value of the building — that is, what it would cost to rebuild it from scratch if it were completely destroyed (not its market value). It is common for older communities to have an outdated figure, meaning that in the event of a total loss they would not receive sufficient settlement. An independent broker such as Segurmar can help you calculate that figure correctly and avoid any unpleasant surprises.
Not sure exactly what your home insurance covers? Message us and we'll review it with you.
We're independent insurance brokers in Marbella. We compare the best options for you at no cost.
Would you rather we reviewed the policy you already have? Review my policy